Maybe your ex handled all the money, and now every login, bill and form is yours alone. The decree is signed, but it doesn't move a single account. Banks, card issuers, 401(k) plans and insurers follow their own paperwork, not your settlement. That's the part of your finances after divorce nobody explains, and it's fixable in a few focused weeks.
The short answer: Work in three passes. This week, separate your bank accounts and close or refinance joint debts, because divorce "doesn't automatically change" your relationship with creditors, according to the Consumer Financial Protection Bureau (CFPB). This month, update every beneficiary form and split retirement accounts with the right court order. By tax time, settle your filing status and who claims the kids.
Key takeaways
- Joint debts stay joint until the lender releases you, whatever the decree says.
- A 401(k) or workplace life policy pays whoever is named on the form, even an ex.
- A qualified domestic relations order can spare you the 10% early withdrawal tax on your share of a workplace plan.
- You may keep your ex's work health plan for up to 36 months, but you must tell the plan.
- Your marital status on December 31 sets your filing status for the year.
This week: separate your money and your credit
Start by making sure your paycheck, your bills and your credit belong only to you.
- Open an account in your name alone. Move your direct deposit and any support payments there, and change every password your ex might know.
- Deal with joint cards and loans. "Sending creditors a copy of your divorce decree doesn't end your responsibility on a joint account," the CFPB says. Your name comes off only if the lender releases you or your ex refinances. An authorized user generally isn't responsible for the balance.
- Pull your credit reports. They're free once a week at AnnualCreditReport.com, according to the CFPB. Look for forgotten joint accounts and late payments on debts your ex now owes.
- Retitle what you kept. The car, the house and any accounts the settlement gave you may need new titles or deeds, and you'll need auto and home or renters insurance in your own name.
Then build a budget on one income with our guide to making a budget for beginners, and let a cash settlement seed an emergency fund.
This month: update every beneficiary form
A beneficiary form, not your decree, decides who gets most retirement accounts and life insurance, so change each one yourself.
- Workplace plans follow the form. Private employers' 401(k)s, pensions and group life policies are generally governed by the Employee Retirement Income Security Act (ERISA). In Kennedy v. Plan Administrator for DuPont (2009), the Supreme Court said the plan "did its ERISA duty" by paying an ex-wife still named on the form, though she'd waived the money in the decree.
- State law may help, but not at work. Some states cancel an ex's designation automatically at divorce: "26 States have by now adopted revocation-on-divorce laws," the Court noted in Sveen v. Melin in 2018, Pennsylvania's among them. But in Egelhoff v. Egelhoff (2001), it held that ERISA overrides a law like this for employer plans.
- Check what the settlement requires. If one of you must keep life insurance to back child support or alimony, leave that beneficiary in place and confirm the amount. Our guide to reviewing your life insurance policy shows where to look, and if your kids are young, see whether a minor can be a life insurance beneficiary.
- Replace your will and powers of attorney. Your ex may still be your executor or your agent under a financial or medical power of attorney. KAV's estate planning checklist lists what to bring to an estate-planning attorney.
This month: split retirement accounts without a tax surprise
A 401(k) or pension is split with a court order, and an individual retirement account (IRA) is split by a transfer. It's worth getting right: for women approaching or in retirement, household income fell 41% on average with divorce, almost twice the drop men saw, a 2012 Government Accountability Office report found.
Workplace plans and the QDRO
A qualified domestic relations order (QDRO) is a court order that gives a former spouse the right to part of an employee's plan benefits. Money paid to you under one is generally taxed to you, and you may be able to roll it over tax-free into your own IRA, according to the Internal Revenue Service's Publication 504. Ask your attorney who's preparing the QDRO and when it goes to the plan.
The IRS normally adds a 10% tax to withdrawals before age 59½. Payments "to an alternate payee under a Qualified Domestic Relations Order" are an exception, but only from workplace plans: the IRS exceptions table marks it "n/a" for IRAs.
Example: where the 10% rule bites
Take Monica, 52, a school office manager in Pittsburgh. She's an example, not a client. Her settlement awards her $80,000 from her ex's 401(k), and she needs $10,000 for a car.
- Cash straight from the plan under the QDRO: the $10,000 is taxable income, with no 10% additional tax.
- Roll it all to an IRA first, then withdraw: the same $10,000 is taxable and adds a $1,000 additional tax.
On these numbers, the order she moves the money in is worth $1,000. Which route fits her return is a question for a tax professional.
IRAs move by transfer
Moving part of an IRA to a former spouse under the decree "isn't considered a taxable transfer," Publication 504 says. Ask the custodian how it handles that before anyone withdraws money.
Within 60 days: sort out your health coverage
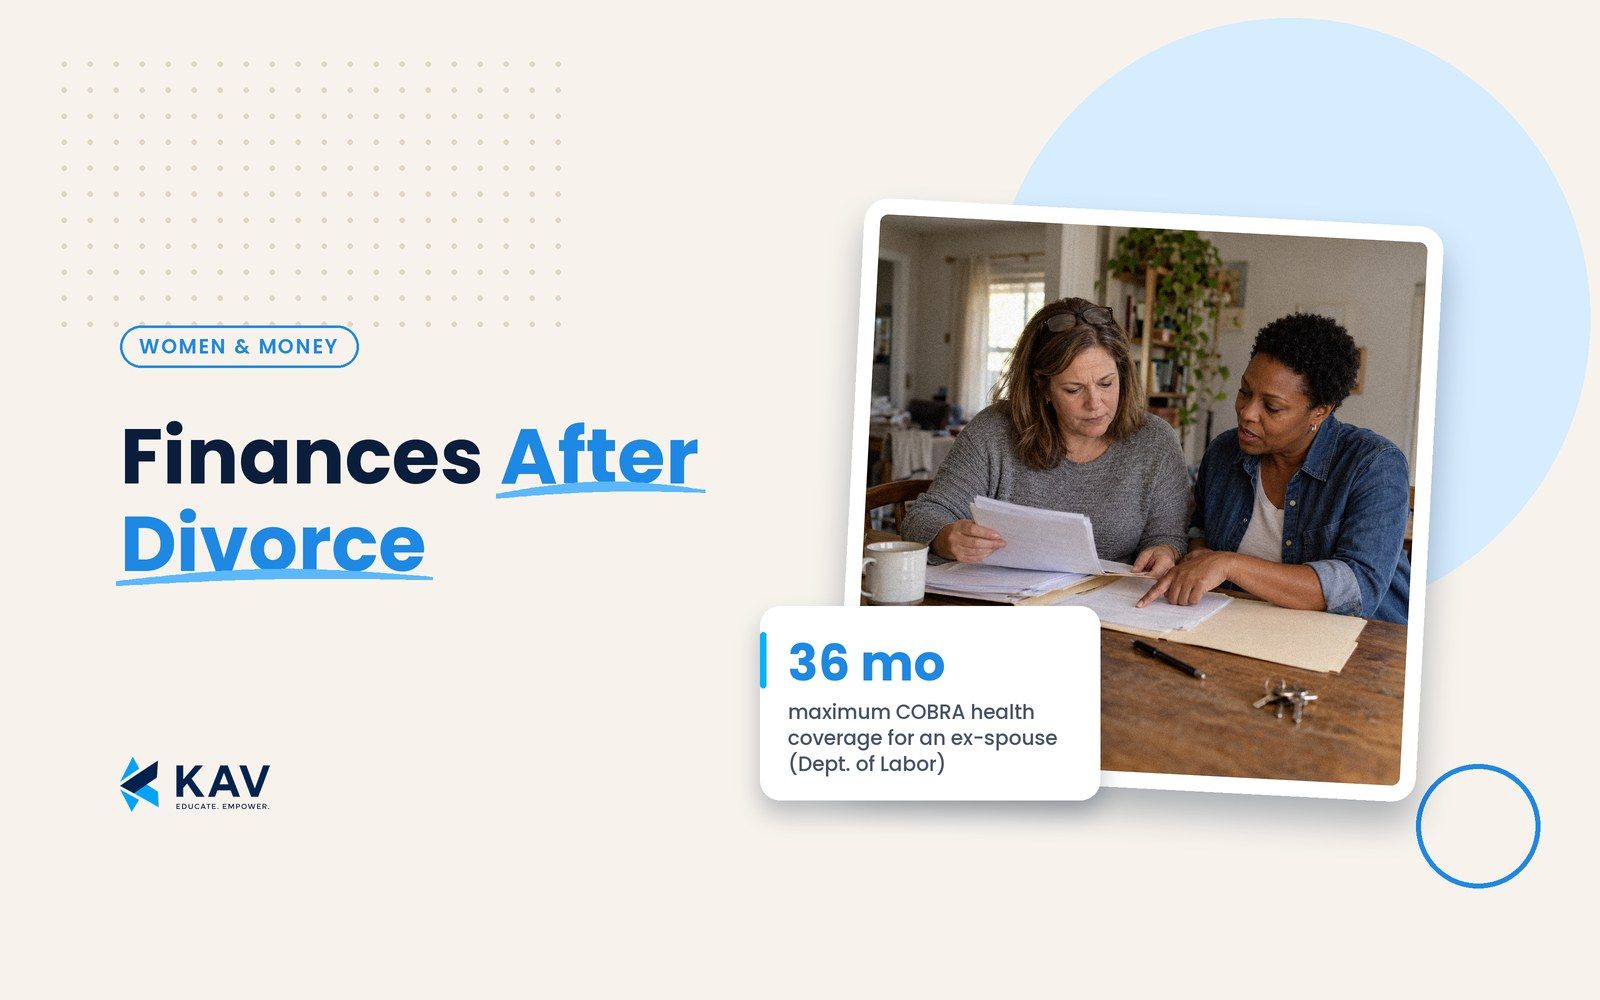
If you were covered through your ex's job, you may be able to keep that plan for up to 36 months, but you have to tell the plan.
- Continuation coverage. Under the Consolidated Omnibus Budget Reconciliation Act (COBRA), divorce is a qualifying event, says the Department of Labor. The plan can't give you less than 60 days to send your notice. The charge can reach 102% of the plan's cost.
- A Marketplace plan. If the divorce ends your coverage, you can enroll from 60 days before to 60 days after you lose it. Divorce without losing coverage "doesn't qualify you," HealthCare.gov says.
- Your own job's plan. Ask HR how and when you can enroll yourself and your kids.
By tax time: filing status, alimony and the kids
Your filing status depends on whether your divorce is final by December 31, the last day of the tax year, according to Publication 504.
- Filing status. With a final decree by December 31, you're unmarried for the whole year. If you paid more than half the cost of keeping up your home and your kids lived there with you more than half the year, you may qualify for head of household, as our guide to financial planning for single moms explains.
- Alimony. Under agreements executed after 2018, alimony isn't deductible for the payer or income for the person who receives it.
- Who claims the kids. The custodial parent is the one the child lived with for "the greater number of nights during the year." Form 8332 can release the dependency claim to the other parent, but not the earned income credit, the dependent care credit or head of household status.
- Your paycheck and your name. Give your employer a new Form W-4, and report a name change to the Social Security Administration.
Finances after divorce: your first five moves
- Open an account in your name and move your paycheck there.
- Pull your credit reports and list every joint account still open.
- Update every beneficiary form, unless your settlement requires your ex to stay on it.
- Ask your attorney about the QDRO, and call the health plan before the 60-day windows close.
- Before Tax Day on April 15, confirm your filing status with a certified public accountant (CPA) or enrolled agent.
If you'd like help turning this into a plan, KAV Solutions offers a complimentary Financial Needs Analysis. A licensed insurance professional walks through how much protection your income and your kids need now, and whose names are on your policies, with you. The analysis is free and you never pay KAV a fee. If you choose to buy a policy, the insurer pays the professional a commission.
KAV's professionals aren't attorneys or tax preparers: your QDRO and will belong with an attorney in your state, and your return with a tax professional.
Frequently asked questions
Can I collect Social Security on my ex's record?
You may, if the marriage lasted at least 10 years, you're 62 or older and you're unmarried now. The benefit can be up to half of what your ex gets at full retirement age, and less if you claim early (Social Security Administration). Divorced at least 2 years? You can claim before your ex applies, if your ex is 62 and eligible (SSA rules).
Is a divorce settlement taxable?
Usually not when you receive it. IRS Publication 504 says no gain or loss is generally recognized on property transferred to a former spouse "incident to your divorce." The catch is basis: you take over your ex's adjusted basis, so a house or stock you keep can carry a tax bill when you sell it.
Who can help with the money side of a divorce?
Each piece has its own professional. A family-law attorney handles the settlement and the QDRO, a CPA or enrolled agent handles taxes, a securities-registered professional handles investments, and a licensed insurance professional can review coverage and beneficiary forms. Ask each one how they're paid.
KAV Solutions is a women-led team of licensed insurance professionals based in Pennsylvania. This article is general education, not individualized financial, tax, or legal advice. Divorce, property and beneficiary rules vary by state, and tax rules are as of October 2026.